This guide is published by Silver Lining Home Buyers, a direct home buyer that may benefit if you choose to sell to us. Compare any offer with your other options and seek independent legal, tax or financial advice when needed. The guide was prepared with AI assistance and does not replace advice for your circumstances.
Sometimes selling a house is less about chasing the highest possible price and more about getting a difficult situation under control.
Maybe the property needs repairs you do not want to manage. Maybe it is vacant, inherited, tenant occupied, or costing you money every month while you decide what to do. Maybe you need to move, settle an estate, or get certainty around a closing date.
In those situations, it can make sense to compare a cash offer with a traditional listing before you commit to either path.
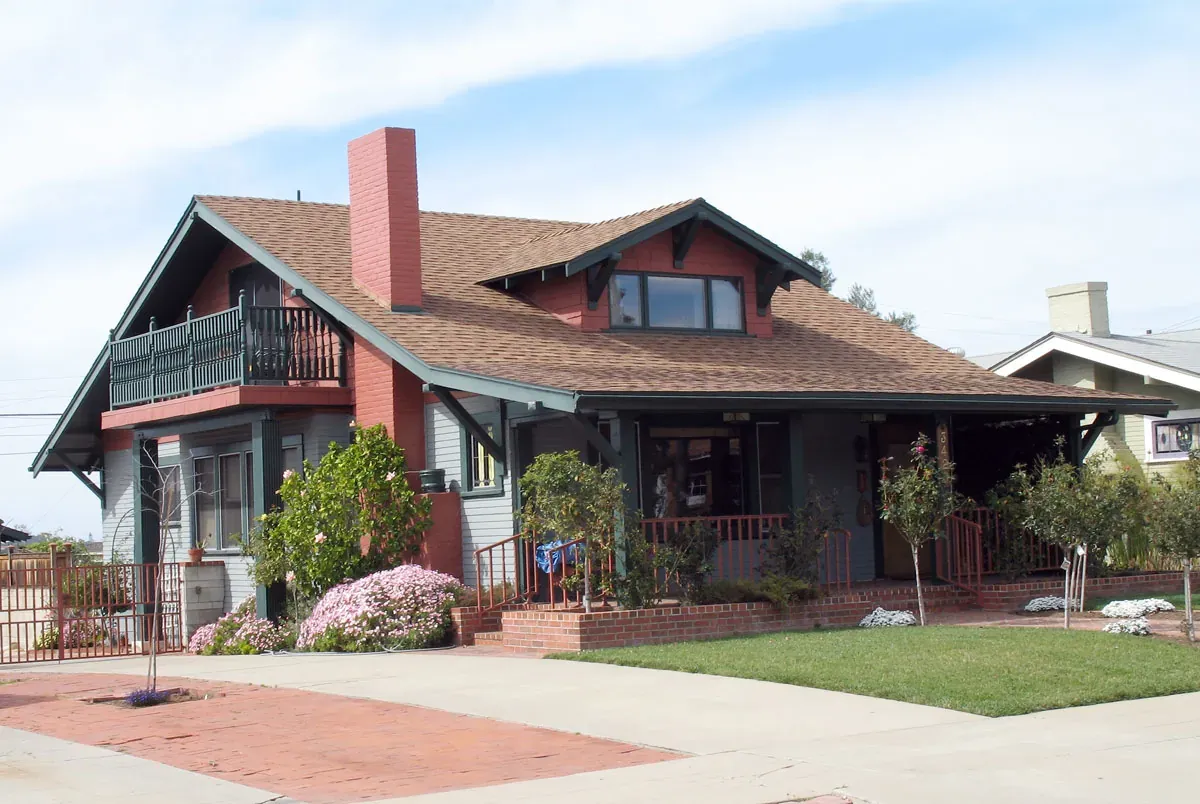
Photo context: a Craftsman-style bungalow in North Park, San Diego. Photo by Allan Ferguson, CC BY2.0, converted to WebP. Illustrative location context, not a Silver Lining property or listing.
Ask Silver Lining whether it will evaluate the property and obtain proposed price, fees, access, condition and timing in writing. Compare the actual offer with a supported listing estimate and other available options.
Cash offer vs. traditional listing
A traditional listing puts the home on the open market and can create broader buyer exposure. It can also involve preparation, showings, inspections, negotiations, buyer financing, and an appraisal.
Verify the actual buyer's funds and any financing, partner-approval or assignment conditions. Read preparation, access, inspection, fees and cancellation terms; a cash label does not establish reduced work or certain closing.
Neither route is automatically better.
If your home is market ready, you have time, and maximizing open-market exposure is your priority, listing with a real estate agent may make more sense.
If the property needs work, you want to sell as-is, or another month of uncertainty is creating a problem for you, comparing a cash offer can give you a clearer second option.
The amount you take home matters more than the asking price
A listing price is a starting point. A written cash offer is a proposed transaction. Compare what you would keep in each case, using realistic assumptions about the same property.
Use supported comparable-property estimates and actual written offers. Include work, negotiated charges, concessions, required payoffs and actual holding expenses. Reconcile principal paid with the closing payoff once, avoid duplicate mortgage escrow or prorations, and keep interim cash needs separate from retained proceeds.
Do not count repairs as a guaranteed increase in resale value. A new kitchen might cost more than it adds to the sale price. Even smaller improvements need a reliable estimate before you spend the money.
You should also ask which party pays escrow, title and other closing charges under each proposal. Cash buyers do not all use the same terms, and a no-repair offer is not automatically free of every selling expense.
If the listed price looks higher but requires months of expenses and work, put those costs beside the cash offer. If selling on the open market still leaves you better off and you can manage the process, that deserves serious consideration.
A sample net-proceeds comparison
Imagine a home where a conventional listing could bring $650,000, while a buyer offers $600,000 for the property as-is. That $50,000 gap sounds decisive until you ask what the seller actually keeps.
For illustration, assume $18,000 in work, $25,000 in selling expenses, $5,000 in concessions and $7,000 in nonprincipal holding expenses for the listing route. That leaves a $595,000 subtotal before required loan or other payoffs, taxes and additional liabilities.
For the comparison only, assume the $600,000 as-is offer has $5,000 in selling expenses and zero work, concessions or holding expenses. Its subtotal is also $595,000 before required payoffs and other liabilities. Actual direct offers may involve those additional costs.
Illustrative comparison before required loan payoff
| Item | Prepare and list | As-is offer |
|---|---|---|
| Assumed sale price | $650,000 | $600,000 |
| Assumed work | -$18,000 | $0 |
| Assumed selling expenses | -$25,000 | -$5,000 |
| Assumed concessions | -$5,000 | $0 |
| Assumed nonprincipal holding expenses | -$7,000 | $0 |
| Illustrative subtotal before required payoffs and other liabilities | $595,000 | $595,000 |
Those figures are examples, not current San Diego prices, quotes or standard fee rates. Real-world results can differ sharply. Commissions are negotiable, contract terms determine expenses, and a property's actual condition affects its value.
The useful lesson is to request a realistic listing analysis and a written cash offer, then compare the net figures alongside the time and work each path requires.
Selling your house as-is
If the thought of fixing the roof, clearing out a property, updating an older kitchen, or coordinating contractors is part of what is keeping you stuck, you can ask for an offer based on the home's current condition.
Selling as-is does not mean condition stops mattering. A home buyer still considers repairs, resale costs, and risk when deciding what the property is worth.
What changes is that you can compare an offer before spending money on improvements.
That can be especially useful if you inherited a property, own a vacant home, have deferred maintenance, or need to make a decision before you have the time or budget for a renovation.
More than one selling option
Selling without renovating does not necessarily mean selling to an investor. An agent can market a home in its present condition, although showings and inspections still take time. Renovating before a listing can be worthwhile when the likely price improvement exceeds the money and work involved.
Some properties may also qualify for a funded renovation arrangement, depending on the provider and contract. Compare who pays for the work, how the costs are repaid, and what happens if the sale takes longer than planned.
An as-is cash offer gives you a written alternative before committing to a renovation or listing. Each path has a different balance of price, time, expense and seller effort.
What to have ready for a first conversation
You can start with the property's address and a brief description of the current condition. Mention whether it is occupied, vacant or rented, and whether you know about any major repairs, prior additions or ownership questions.
If you have recent photos, an inspection report, a repair estimate or property records, those can help. They are not a reason to postpone making contact if you do not have them yet.
Be clear about your priorities as well. Some homeowners need a firm date because they are relocating; others can wait but do not want to pay for repairs. A buyer can only offer a relevant option if those details are understood.
You can request a property review to compare what is available before deciding whether to list.
What Silver Lining looks at before making an offer
A useful property review starts with what is actually happening with the home.
That includes the address, property type, occupancy, known condition issues, repairs you already know about, and the timing you have in mind. Public property information and comparable sales may also be relevant.
You do not need to diagnose every problem before reaching out.
If the roof leaks, the property has been vacant, a tenant is still living there, or an addition was made years ago and you are unsure about the paperwork, say so. Clear information helps everyone understand the property and compare realistic options.
Deciding whether a repair is worth paying for
A repair does not have to be major to affect how a house shows, but spending money is not the same as adding value. Before replacing floors, renovating a bathroom or doing cosmetic updates, compare a contractor's written estimate with the likely difference in sale price.
Ask what the work includes and whether the quote might change once walls or flooring are opened. Think about the time needed to schedule the crew and whether you would still have to carry the property's regular bills during that period.
There is also a middle ground. You may be able to handle a few safety or presentation issues and list the rest as-is. Or you may decide not to take on any of the work. Neither decision should be made from a generic rule that repairs always pay for themselves.
For houses inside the City of San Diego, the city's Development Services department offers ways to search permit and project records. Looking up what is known about an old addition or major past renovation can be useful before asking for estimates.
When a cash home buyer may be worth considering
Homeowners usually start looking for a cash buyer because something about the normal selling process feels difficult, slow, expensive, or uncertain.
Some common selling situations include:
- A house that needs major repairs
- An inherited or probate property
- A vacant home that keeps creating monthly costs
- A tenant occupied property
- A property with years of deferred maintenance
- A move or life change that makes timing more important
- A seller who does not want to prepare the house for repeated showings
None of these situations means you have to sell for cash. They are reasons to compare your options sooner rather than letting the property keep creating stress or expense while nothing changes.
Situations that change the selling process
An inherited home can involve family decisions, estate documents and questions about who can sign. A buyer may evaluate the house in its present condition, but the ownership steps still need to be resolved.
Vacant houses can keep generating insurance, taxes, utilities and maintenance costs. If you live elsewhere, organizing repairs and appointments from a distance creates extra work.
If tenants occupy the property, the existing lease, access and applicable tenant protections matter. A sale does not itself mean the occupants must leave.
Be specific about the condition issues you know, and clear about anything you have not yet checked. A realistic offer begins with realistic information.
What the process looks like
Start by sharing the property details you already know.
Ask whether Silver Lining will consider the property and which assessment terms, fees or obligations apply. Compare any written offer with a supported listing estimate and other actual proposals.
Before signing anything, read the actual terms. Pay attention to the purchase price, deposit, property review rights, closing costs, target closing date, and any provision that allows the buyer to change or cancel the agreement.
If you want to understand the process first, see how it works.
Check the written offer before you sign
Check the actual funding, title, inspection and cancellation conditions. A cash description alone does not establish waived mortgage approval, waived contingencies or a guaranteed date.
Ask who is named as the buyer, whether they have funds available, and whether they intend to close themselves or assign the contract. Ask when any inspection or review period ends and exactly what might allow the purchase price to change.
Look at the deposit, escrow arrangements, target closing date, cancellation terms and each party's share of closing expenses. A written estimate of your proceeds makes it easier to compare two offers that have different headline prices.
If anything is unclear, review the agreement with a professional who represents your interests. You do not need to make a decision based only on a verbal promise or an advertised closing timeframe.
Selling as-is still involves California disclosures
The phrase as-is generally describes the condition in which the buyer proposes to purchase the house. It does not automatically eliminate disclosures required in a California residential sale.
The California Department of Real Estate's 2026 Real Estate Law excerpts include the transfer disclosure provisions and applicable exceptions. Confirm what your particular transfer requires rather than assuming that selling to a cash buyer removes every disclosure.
Clear records and accurate descriptions of known property issues can help prevent surprises later in the process.
Frequently asked questions
Do I have to accept an offer after requesting one?
Confirm whether requesting or authorizing an assessment creates a fee or other obligation. Have counsel explain the effect of accepting, countering or signing the actual proposal before responding.
Can I sell my house as-is without making repairs first?
A home buyer may purchase the property in its current condition. The condition still affects the offer, so compare the as-is option with the cost, time, and uncertainty of repairing before you sell.
Does a cash offer mean there are no closing costs?
Not automatically. The written offer should state which party pays each cost. Compare expected net proceeds rather than assuming every cash sale uses the same fee structure.
Can I choose the closing date?
The parties can agree on a target closing date. Title, ownership, access, or other transaction issues can still affect timing, so the written agreement controls.
Should I take a cash offer or list with an agent?
It depends on the property and your priorities. Compare expected net proceeds, repair work, timing, seller effort, market exposure, and the risks in each path.
See what your options look like
If the house has become one more problem you need to solve, getting real numbers can make the decision easier.
Share the actual property details and ask whether Silver Lining will evaluate it. Confirm assessment terms, fees and obligations before proceeding.
Request an offer to discuss the property and next steps.